


From new and expectant parents planning for the future to children starting kindergarten, stepping up to high school, or moving into a freshman dorm, back-to-school season means something different for every family.
And so does a 529 plan.
A 529 combines the power of tax-free investing with the flexibility to adapt to each child’s unique journey from K-12 through college and beyond.
With students now heading back to class and College Savings Month in full swing, three 529 experts at different life stages share their experiences. Discover how they’re using 529 accounts – and how it applies to your education plans.
Kids in college and beyond: Paying a broad range of expenses
Our two sons could be poster children for a 529 plan’s flexibility.
Our firstborn took a traditional route to college and graduated debt-free last May with a bachelor’s degree. We opened his account a year before he was born, made regular monthly investments, and doubled down during high school to avoid falling short. The 529 ended up covering all tuition and housing costs, with enough left over to kick-start his retirement savings. We basically did everything right.
And then we did everything wrong with our younger son. He has disabilities, and we never thought he’d go to college. It wasn’t until middle school that we finally opened his 529 account, using the special five-year gifting option to make up for lost time.
It’s a good thing we did. After one difficult semester at a four-year university and a summer of online classes through community college, our son is now studying media and music at a city college. Through it all, our 529 has been there to pay every qualified expense, including a special needs counselor and even his music equipment.
There’s no greater gift than giving your children the freedom to choose the right schools for them. My hope is for every family to feel that same sense of comfort with their loved ones. Here’s my advice:
- Don’t procrastinate. Regardless of your family’s situation, your kids are likely to go to college. And if they don’t, a 529 plan gives you plenty of options. You could name another family member as the account beneficiary. You could use the funds for other qualified education expenses, such as apprenticeships, career credentialing programs, or a sibling’s student loans. You can even transfer eligible amounts to a Roth IRA to give kids an early start on retirement.
- Put college savings on autopilot. There will always be a reason to skip 529 contributions. Set up automatic investments to stay on track when everyday life tries to derail your plans.
- Find ways to save more. You think you can’t, but you can. For example, instead of investing once a month, consider contributing part of each paycheck, along with tax refunds, bonuses, gifts, and other extra money. You’ll be surprised how it adds up over the years.
Tricia Scarlata
Head of 529 Education Savings, J.P. Morgan Asset Management
Kids in high school: Ramping up 529 contributions
College is starting to feel very real now that our 15-year-old daughter is in high school. It’s exciting and terrifying and every emotion in between.
Fortunately, we have been preparing financially since opening a 529 account shortly after she was born. As college gets closer, we are becoming more diligent about increasing investments. In addition to automatic monthly deposits, we are now making quarterly catch-up contributions to boost her account.
A 529 plan is a great way to get family and friends involved, too. In our case, my mom has been funding a second account for our daughter through a combination of payroll deductions, monthly contributions, and gifts.
Between those two accounts and the money currently allocated toward private high school, we hope to pay for all four years of college. If everything goes well, we may even have enough for an advanced degree or Roth IRA rollover. We will continue adding to our 529 during college years to replace some of what we withdraw and to take advantage of state income tax deductions.
In hindsight, I wish we had invested more when our daughter was younger to maximize tax-free compounding. Having said that, I would also tell families that it’s never too late to get started or save a little more. Even if college is coming soon, you still have time to put a nice dent in the expenses – and ease the debt burden on your kids and grandkids.
Greg Starita
529 Relationship Manager & Investment Specialist, J.P. Morgan Asset Management
Kids in the future: Getting a head start on college savings
After just one week working in the 529 space, I was sold. I had gotten married only a month earlier. Even though my wife and I don’t expect kids for a few more years, we already opened a 529 account, with me listed as beneficiary until our first child arrives.
For me, getting started early wasn’t about trying to predict the future. It was about giving ourselves more time for compounding and for building good savings habits before life gets busier.
Reviewing J.P. Morgan Asset Management’s college planning guide was all the motivation I needed. Today, we’re making modest monthly contributions and plan to increase them over time. I’m also fortunate that both my parents and my in-laws have opened accounts for their future grandchildren.
What appealed to us most is the flexibility. A 529 eases the uncertainty of saving for a future still many years away. We hope to send at least two children to college someday, but if our plans change, our 529 accounts will adapt with us.
That’s why I encourage other young couples to start saving sooner rather than later, even if it’s only a small amount each month. Don’t let the “what-ifs” stop you, and don’t feel like you need to cover every future college expense on your own. Save what you can, automate the process, and make it a habit. Over time, small contributions add up, and a consistent plan can make a meaningful difference.
Joe Schulman
529 Relationship Manager & Investment Specialist, J.P. Morgan Asset Management
About the authors:
Tricia, Greg and Joe are members of the 529 Education Savings team at J.P. Morgan Asset Management, where they support families and financial professionals planning for college. J.P. Morgan Asset Management serves as investment manager for two 529 plans and produces the award-winning1 College Planning Essentials guide to help investors make well-informed decisions with their education dollars.
Disclosures
1 Gramercy Institute, Financial Content Marketing, Business-to-Multi-Target Single-Country Award, Asset Management Marketing, Focus Award Single-Country Collateral, Fall 2025.
This is a general communication being provided for informational purposes only.
It is educational in nature and not designed to be taken as advice or a recommendation for any specific investment product, strategy, plan feature or other purpose in any jurisdiction, nor is it a commitment from J.P. Morgan Asset Management or any of its subsidiaries to participate in any of the transactions mentioned herein. Any examples used are generic, hypothetical and for illustration purposes only. This material does not contain sufficient information to support an investment decision and it should not be relied upon by you in evaluating the merits of investing in any securities or products. In addition, users should make an independent assessment of the legal, regulatory, tax, credit, and accounting implications and determine, together with their own financial professional, if any investment mentioned herein is believed to be appropriate to their personal goals. Investors should ensure that they obtain all available relevant information before making any investment. Any forecasts, figures, opinions or investment techniques and strategies set out are for information purposes only, based on certain assumptions and current market conditions and are subject to change without prior notice. All information presented herein is considered to be accurate at the time of production, but no warranty of accuracy is given and no liability in respect of any error or omission is accepted. It should be noted that investment involves risks, the value of investments and the income from them may fluctuate in accordance with market conditions and taxation agreements and investors may not get back the full amount invested. Both past performance and yields are not reliable indicators of current and future results.
To the extent permitted by applicable law, we may record telephone calls and monitor electronic communications to comply with our legal and regulatory obligations and internal policies. Personal data will be collected, stored and processed by J.P. Morgan Asset Management in accordance with our privacy policies at https://am.jpmorgan.com/global/privacy.
J.P. Morgan Asset Management is the brand name for the asset management business of JPMorgan Chase & Co. and its affiliates worldwide.
If you are a person with a disability and need additional support in viewing the material, please call us at 1-800-343-1113 for assistance.
I spent this past weekend attending graduation parties for recent high school graduates and mingling with parents who, in a few short months, will be sending their first children off to college. As parents, we spend so much time in the preparation — putting away savings in 529 plans during elementary school for what seems at the time like a distant future, followed by years of supporting our children through the gauntlet of qualifying for, applying to, and selecting a college — that when graduation day finally arrives, we feel like we’re done! The reality, however, is … well, not quite yet.
Your student very likely already has the university-provided checklist well in hand, covering housing, orientation enrollment, class selection, and — most importantly — identifying cool roommates. Let them run with that. But dear parent, heed some well-worn advice on practical, parental to-dos to cover with your student over the summer before you leave them on move-in day:
Talk about money. If your student has never managed a budget, this is a perfect time to learn. Define your financial boundaries and responsibilities for school-year expenses. Determine who will pay tuition and housing bills, and discuss what constitutes “core” versus “discretionary” spending, as well as how your student will supplement expenses beyond a possible base allowance — perhaps by getting a campus job.
My own experience involved saving to cover tuition and housing expenses through 529 plans, and, beyond that, providing each of my sons with a year’s budget funded at the start of the academic year, meant to last the entire year — anything above and beyond was funded out of their own pockets.
Discuss a FERPA waiver. The Family Educational Rights and Privacy Act (FERPA) is a federal law enacted in 1974 that protects the privacy of student education records. It requires your student’s prior written consent before a university may disclose grades, transcripts, class schedules, and financial aid records to you. In other words, information you had unlimited access to when your student was in high school is no longer available to you once they reach college — without their explicit consent. FERPA waivers are available through the college or university and may even be signable online. Importantly, a FERPA waiver allows the student to selectively choose what types of information to share with their parents — it is not a blanket waiver — so your student retains meaningful control.
Have your student sign a HIPAA release form and a health care proxy. Once your student turns 18, they are legally recognized as an adult, and health care providers are bound by federal privacy laws under HIPAA, which prevent them from disclosing medical records or acting on your direction during an emergency without explicit legal authorization. A student who wants a parent to have access to medical records, lab results, and treatment plans must grant that authorization by signing a Health Insurance Portability and Accountability Act (HIPAA) release form. Additionally, if a student becomes incapacitated, a health care proxy must be in place for a parent to have standing to make medical decisions. These two steps are best taken when you are not already in a medical or emergency crisis.
Talk about mental health. The transition out of the home and into the independence of college life can be both emotional and stress-inducing. Normalize this possibility, and find out what academic, health, and mental health support services are available at your student’s school — where they are located and what they provide. Being familiar with these services in advance may help your student address academic or personal challenges before they escalate. Many students are reluctant to seek help because they fear it signals that they are struggling or unable to handle their responsibilities; knowing where to turn ahead of time lowers that barrier.
I experienced this firsthand when my son, who attended a university four hours from home, needed support services. I was relieved to have had a health care proxy in place, which allowed me to help him find the services he needed. Through that experience, he learned how to advocate for himself and navigate the system to get the help he deserved.
I call this the business of launching your student into college life. Taking care of these items in advance gives you, as a parent, genuine peace of mind — and gives your student the single-minded focus they need to embrace their new adventure, grow into adulthood, and create the lasting memories that college is all about.
About the Author:
Vivian Tsai is Managing Director and Head of Relationship Management for TIAA-CREF Tuition Financing, Inc. (TFI), a wholly owned subsidiary of TIAA. TFI operates as the 529 Plan Program Manager for the States of California, Colorado, Georgia, Illinois, Kansas, Michigan, Minnesota, Oklahoma, Washington and Wisconsin. She resides in California having parented her sons through California State Polytechnic University in San Luis Obispo and the University of California at Berkeley.
By Nick Thiros, Senior Institutional Relationship Manager, Ascensus
For the past ten years, I’ve had the privilege of educating Idahoans about the benefits of the Idaho 529 plan. Whether I’m meeting with large employers in cities or small businesses in rural communities, one theme always rises to the surface: people want saving for education to feel easier. And employers want to support their teams without adding administrative burden or cost.
Throughout my work partnering with hundreds of companies across the state, I’ve seen firsthand how 529 plans can make a meaningful difference—both for employees and for the organizations that support them. As employers continue seeking smart ways to attract and retain talent, offering a 529 plan has proven to be a simple, impactful addition to any benefits package.
Payroll Direct Deposit: A Simple Benefit Employees Actually Use
One of the most surprising things for many employers is just how easy it is to add their state’s 529 plan as a payroll direct deposit option. There’s no cost to the employer, no complex administrative process, and in many cases, employees can set it up themselves through a self-service HR portal.
For companies without a self-service system, HR or payroll can assist with the initial setup—and from that point forward, the process essentially runs itself. The automation alone is a game changer for employees: one less thing to remember and one more step toward building their education savings.
And “employees” aren’t just job titles. They’re parents, grandparents, aunts, uncles, godparents—and many are saving for their own education as well. Education is lifelong, and at some point, all of us need to learn something new or upskill for the next stage of our careers. That’s part of what makes 529 plans so powerful: they support education at every stage of life.
Employer Contributions: A Growing Opportunity
Employer contributions to 529 plans are still relatively new in the industry, but the momentum is undeniable. Eight states now offer tax incentives to employers who contribute to employees’ 529 accounts. For instance, in Idaho, companies can claim a 20% state tax credit on contributions to employees’ Idaho 529 accounts, up to $500 per employee per year.
These contributions can be structured creatively—much like a 401(k) match—or offered as one-time awards tied to milestones or life events. One employer I work with contributes when an employee welcomes a new baby. It’s a simple, meaningful way to celebrate a major moment while supporting a family’s future education needs.
Employer contributions have become my passion over the years (just ask my coworkers). Companies appreciate having a one-stop shop benefit that helps employees save not only for their loved ones’ education, but also for their own professional development. And with the recent passage of H.R. 1, 529 plans can now support even more education-related expenses, including professional licensing and continuing education requirements.1
Why It Matters
Offering a 529 plan as a workplace benefit adds immediate credibility and removes uncertainty for employees who may be hesitant about investing. Many of us already manage our retirement, health, and other benefits through our employer—it only makes sense to manage our education savings there as well.
Employees deeply value benefits that support their long-term goals, their families, and their future. A workplace 529 plan does exactly that. It’s a benefit that tells employees, “We’re investing in your growth—and in the people who matter to you.”
Where to Begin
If you’re an employer interested in adding a 529 plan to your benefits package, reach out to your state 529 plan; they’ll guide you through the process. And if you’re an employee who wants your organization to consider offering a 529 benefit, start the conversation with your HR team. Many employers simply don’t know how easy and valuable it can be.
I’m excited to see how workplace adoption of 529 plans continues to grow in the years ahead—and I plan to be front and center, helping Idaho employers support the people who move their organizations forward.
About the Author
Nick Thiros serves as a Senior Institutional Relationship Manager at Ascensus, representing the IDeal – Idaho College Savings Program. Since joining Ascensus in 2015, Nick has leveraged his CPA background and strong relationships across Idaho’s business community to help employers implement meaningful education savings benefits. He is recognized as a subject matter expert on 529 plans and a trusted resource for organizations throughout the state.
Footnotes
1Qualified postsecondary credentialing expenses generally include tuition, fees, books, supplies, and equipment required to enroll in or attend a recognized postsecondary credential program, and fees for testing and continuing education if required to obtain or maintain a recognized postsecondary credential. For a program or credential to be considered recognized it must meet certain criteria. Please refer to the 529 Plan’s Program Description for important additional information describing the tax treatment of distributions taken for postsecondary credentialing expenses.
Jackie James, Director, TIAA-CREF Tuition Financing, Inc. (TFI)
Program Marketing
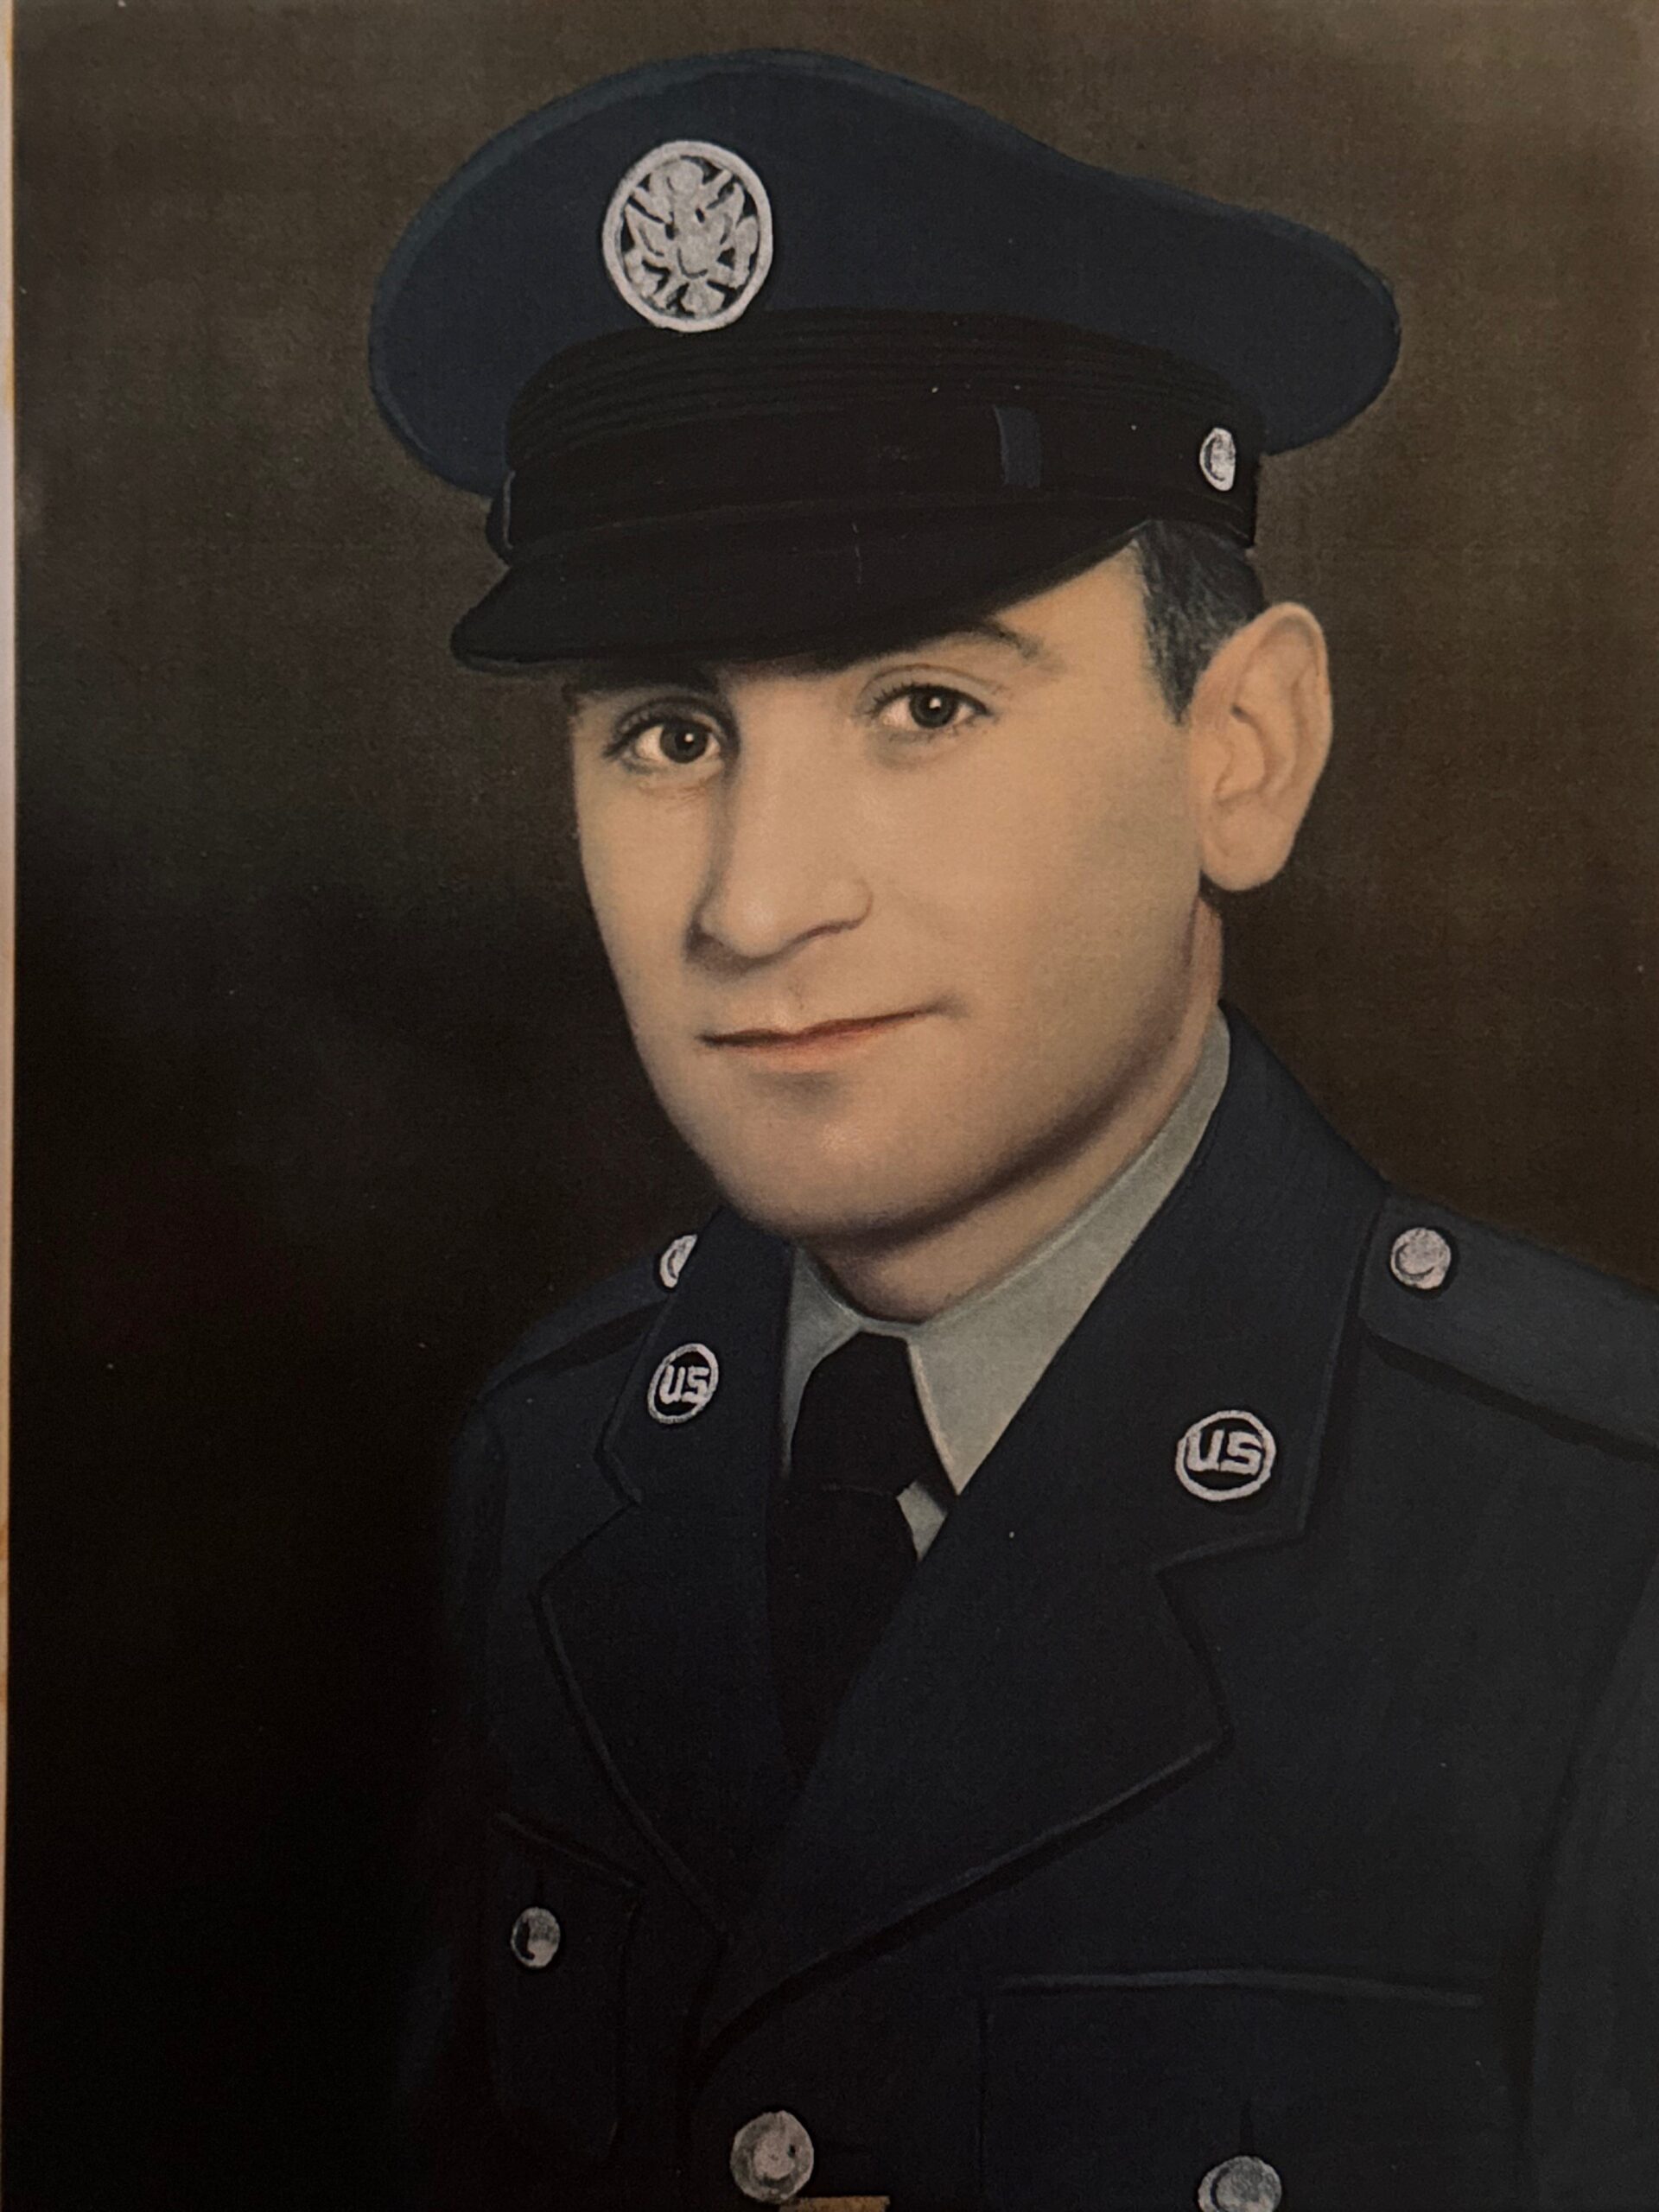
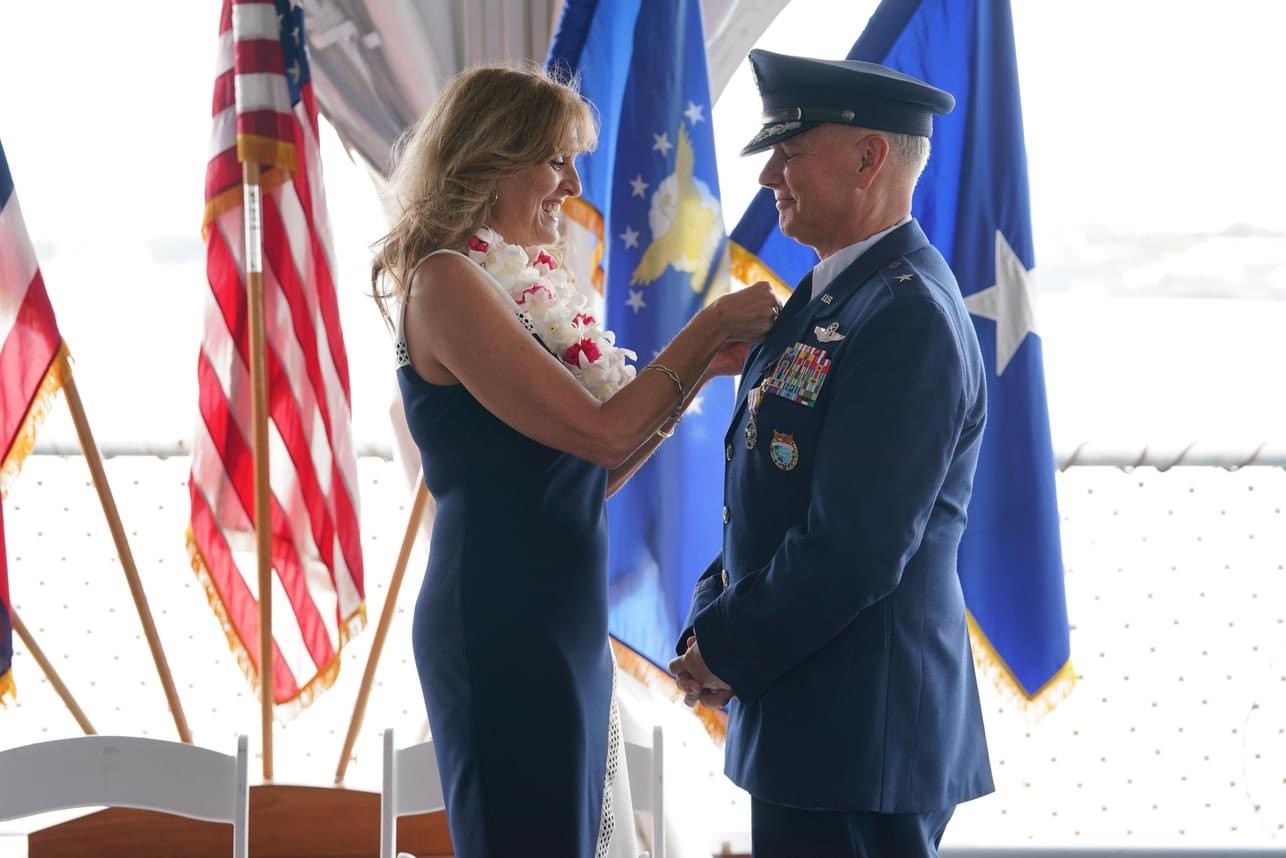
As someone who grew up in a military family, I have seen firsthand how military education benefits can transform lives across generations. Both of my grandfathers served our country. My dad retired as a Brigadier General from the US Air Force and the Air National Guard, and my brother is currently serving. Through their experiences, I’ve learned that veterans earn well-deserved educational benefits with the GI Bill. However, many do not realize how combining their GI Bill benefits with 529 college savings plans can create a powerful strategy for maximizing educational opportunities.
The GI Bill Foundation I Grew Up Understanding
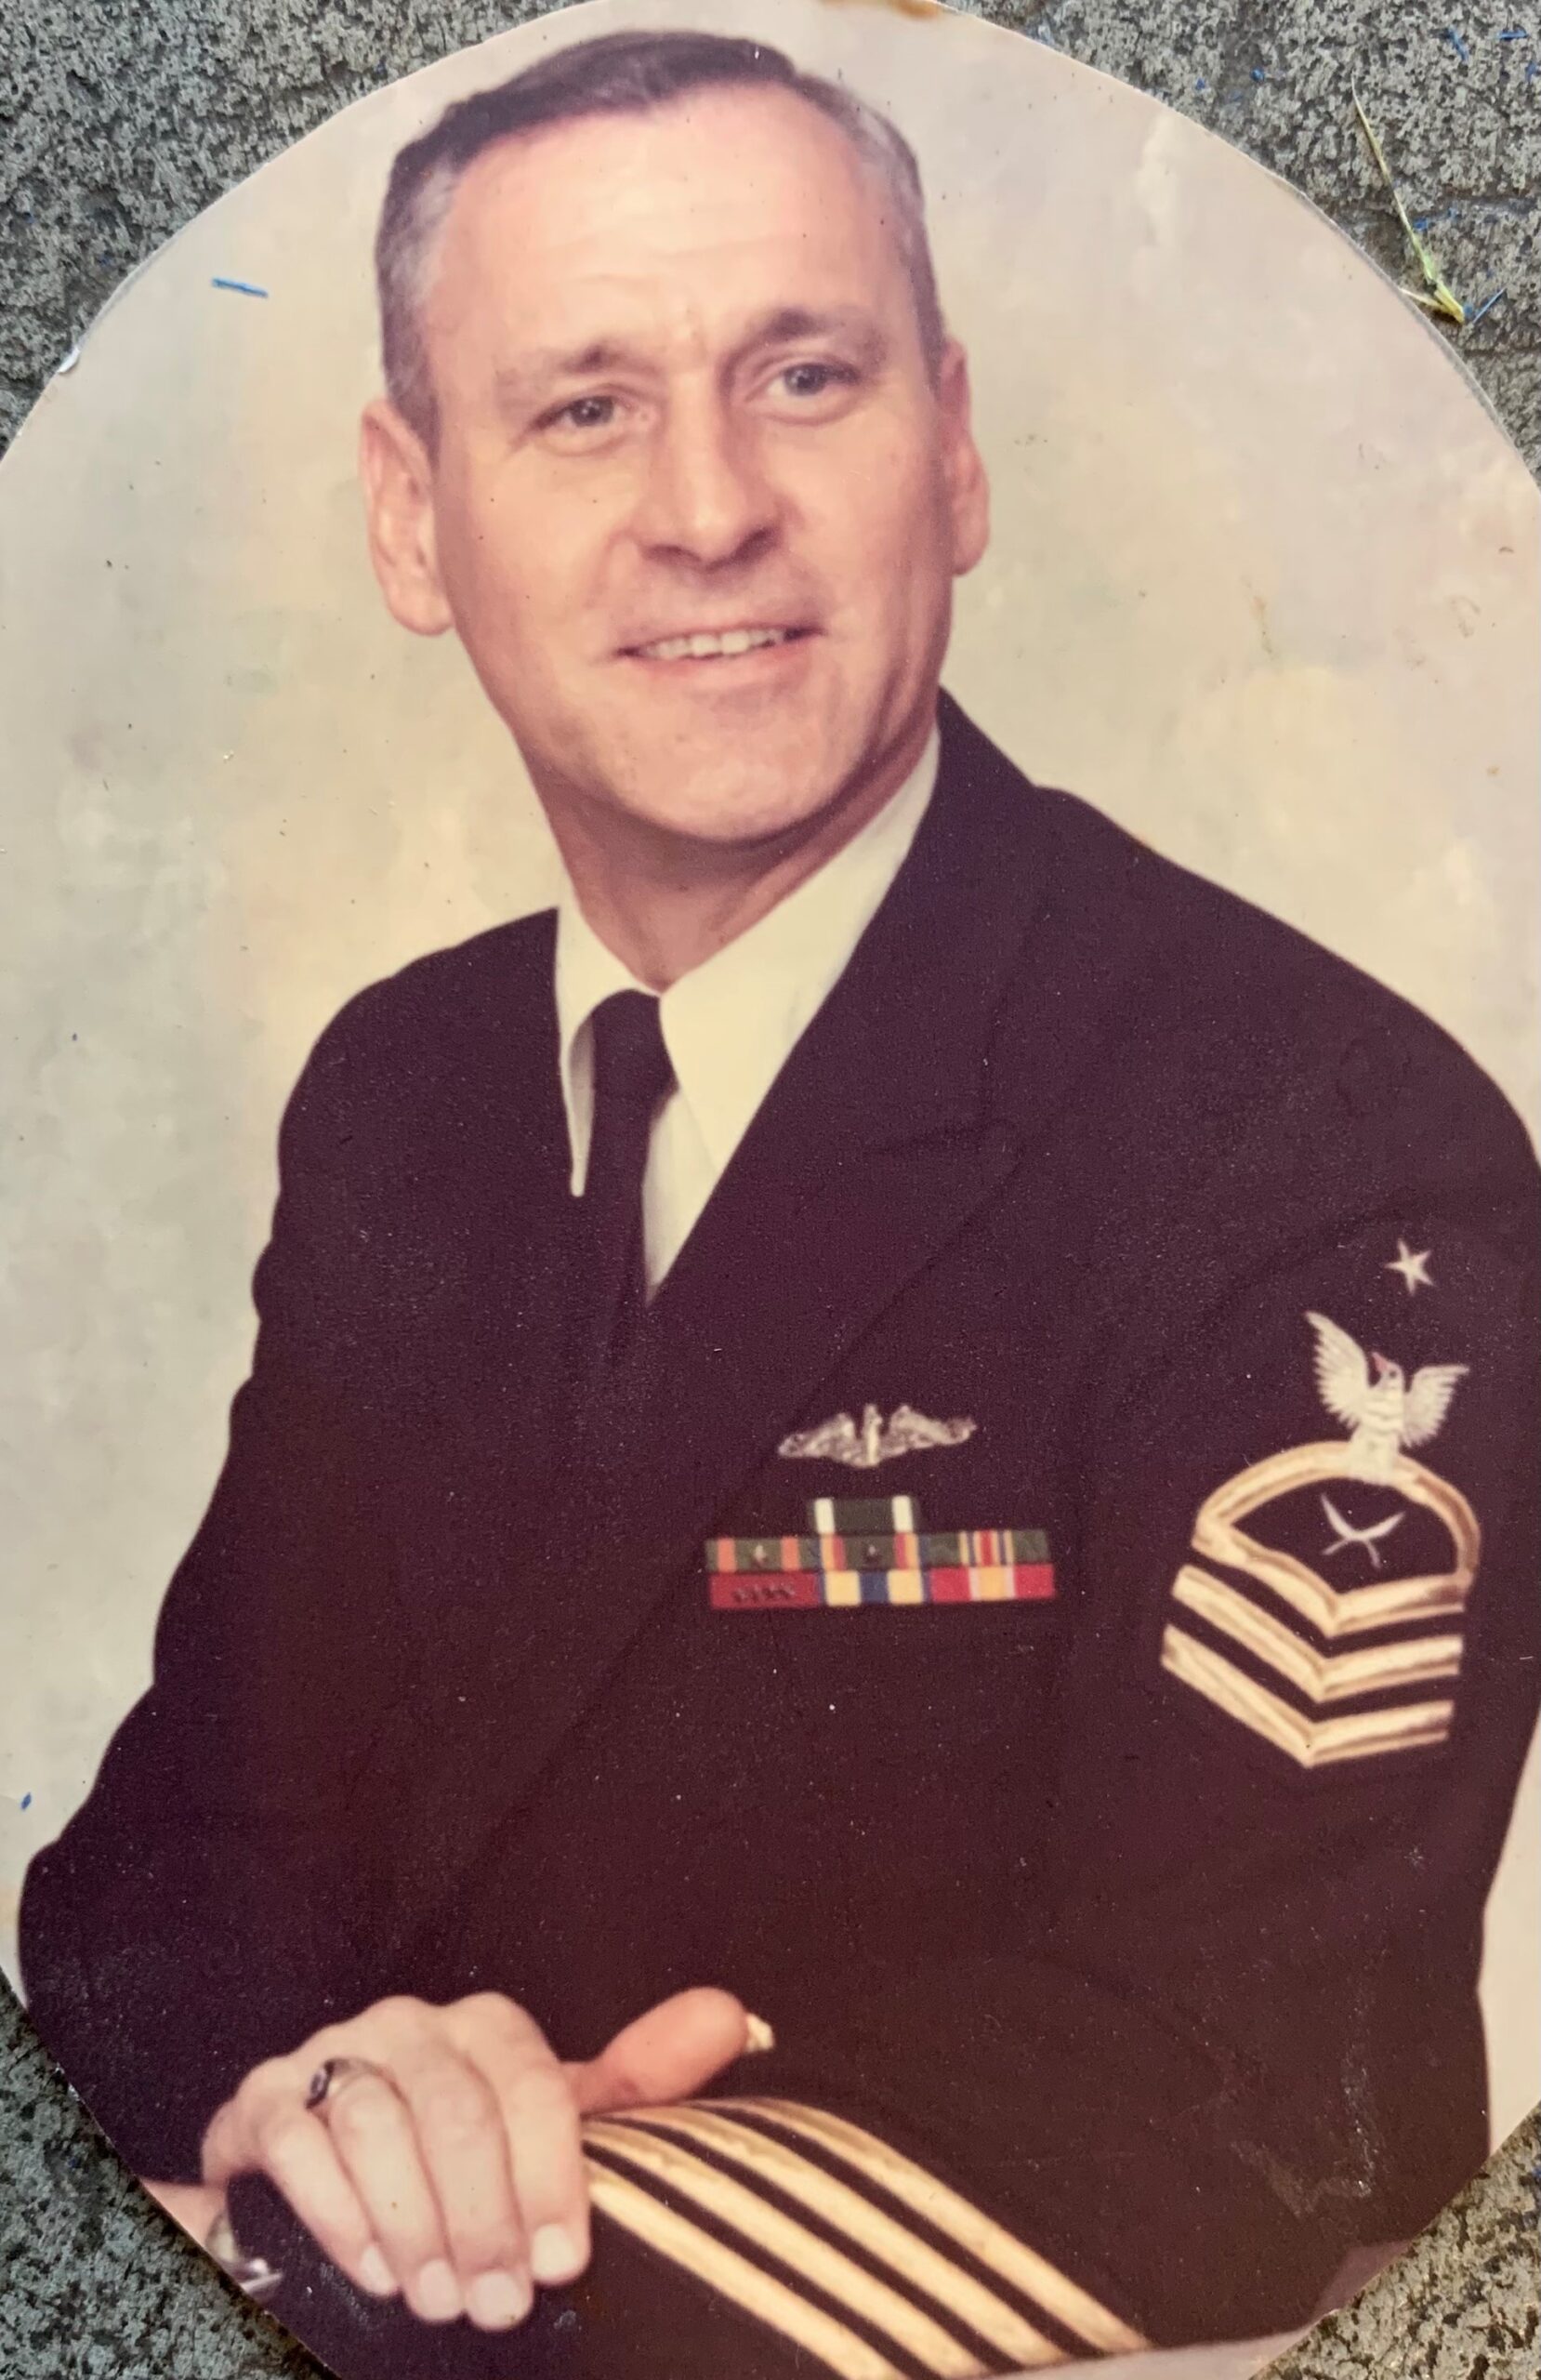
Growing up, I watched my dad navigate his military education benefits and learned how the Post-9/11 GI Bill provides funding for tuition and a monthly stipend for other expenses such as housing, books and supplies. 1 These benefits can be used for undergraduate degrees, graduate programs, vocational training, and certification programs. Although there are several different GI Bills, what makes the Post-9/11 GI Bill particularly valuable, and why my dad decided to use it, is its transferability feature – something my mom and dad discussed extensively as they considered how to best support their children’s educational goals.
My parents made the decision to transfer his GI Bill benefits to cover my and my brothers’ higher education expenses. Two of us attended an in-person 4-year college, while one pursued flight training and earned an online degree from a 4-year college. Thanks to his military benefits and his forward-thinking financial skills, we were all able to graduate with no debt – a tremendous gift that has shaped our financial futures.
The Post-9/11 GI Bill provides 36 months of education benefits – enough to cover a typical four-year degree when used efficiently. However, this creates an important planning consideration for military families, especially those with multiple children who could benefit from these educational resources. Once a veteran transfers or uses any portion of their 36-month benefit, those months are permanently expended, whether used by the veteran themselves or transferred to a spouse or child.1
This means families with multiple potential beneficiaries must make strategic decisions about how to allocate this valuable but limited resource. When GI Bill benefits are exhausted – whether after 36 months or when split among family members – any remaining educational expenses must be covered through savings, investments, personal funds, loans, or other financial aid.1
This is precisely where 529 college savings plans can become invaluable, providing a reliable funding source to bridge gaps when GI Bill benefits run out or to fund education for additional family members who may not receive transferred benefits.
How 529 Plans Can Enhance Military Benefits
Through my family’s planning process, I learned that a 529 plan can serve as the perfect partner to GI Bill benefits. These tax-advantaged college savings accounts allow families to save and invest for qualified education expenses, with earnings growing tax-deferred at both the federal and state levels, and withdrawals remain tax-free when used for qualified expenses.
529 plans can offer several strategic advantages.
First, they can cover expenses that exceed the GI Bill limits, such as the difference between private school tuition and the maximum benefit amount.
Second, 529 funds can pay for expenses beyond the 36-month allotment, helping families pay for multiple beneficiaries who want to further their education.2
Maximizing Both Benefits
Planning allows veterans to optimize both resources, something I’ve observed across three generations of military service in my family. Consider using GI Bill benefits for the most expensive educational goals – perhaps a child’s four-year degree at a state university where the benefit provides maximum coverage. Meanwhile, 529 plans can supplement these benefits or fund the education of additional family members.
Alternatively, since the GI Bill benefits do have a limit, consider using each month’s allotment strategically: apply the GI Bill toward a beneficiary pursuing more expensive degrees, while utilizing 529 plan savings to cover lower-cost options for other beneficiaries, such as technical programs, professional certifications, or apprenticeships.3
The recent SECURE Act 2.0 can add even more flexibility to 529 plans, allowing unused funds to be rolled over to a Roth IRA under certain conditions, providing a retirement savings alternative for military families who prioritize college savings.4
State-Specific Benefits
Many state 529 plans offer additional benefits for families. Some states provide matching contributions or tax deductions/credits for contributions made into a 529 plan. Prior to investing, Veterans should check with their current state of residence to learn if it offers tax or other benefits, such as financial aid, scholarship funds, or protection from creditors, for investing in its own 529 plan.
Getting Started: Advice from a Military Family
Veterans interested in maximizing their educational benefits should start by understanding their specific GI Bill entitlements and transfer options. Then, research a 529 plan and how different plans compare. Many financial advisors specialize in military benefits and can help create comprehensive strategies that optimize both the GI Bill and 529 plan advantages.
The combination of earned military benefits and strategic 529 plan savings can create powerful opportunities for veterans and their families. Having witnessed this across generations in my own family, I know that understanding how these programs work together can help ensure that military families make the most of every educational dollar available to them.
To all the veterans and active service members reading this – thank you for your service and may these educational benefits serve as a pathway to bright futures for you and your families.
About the Author
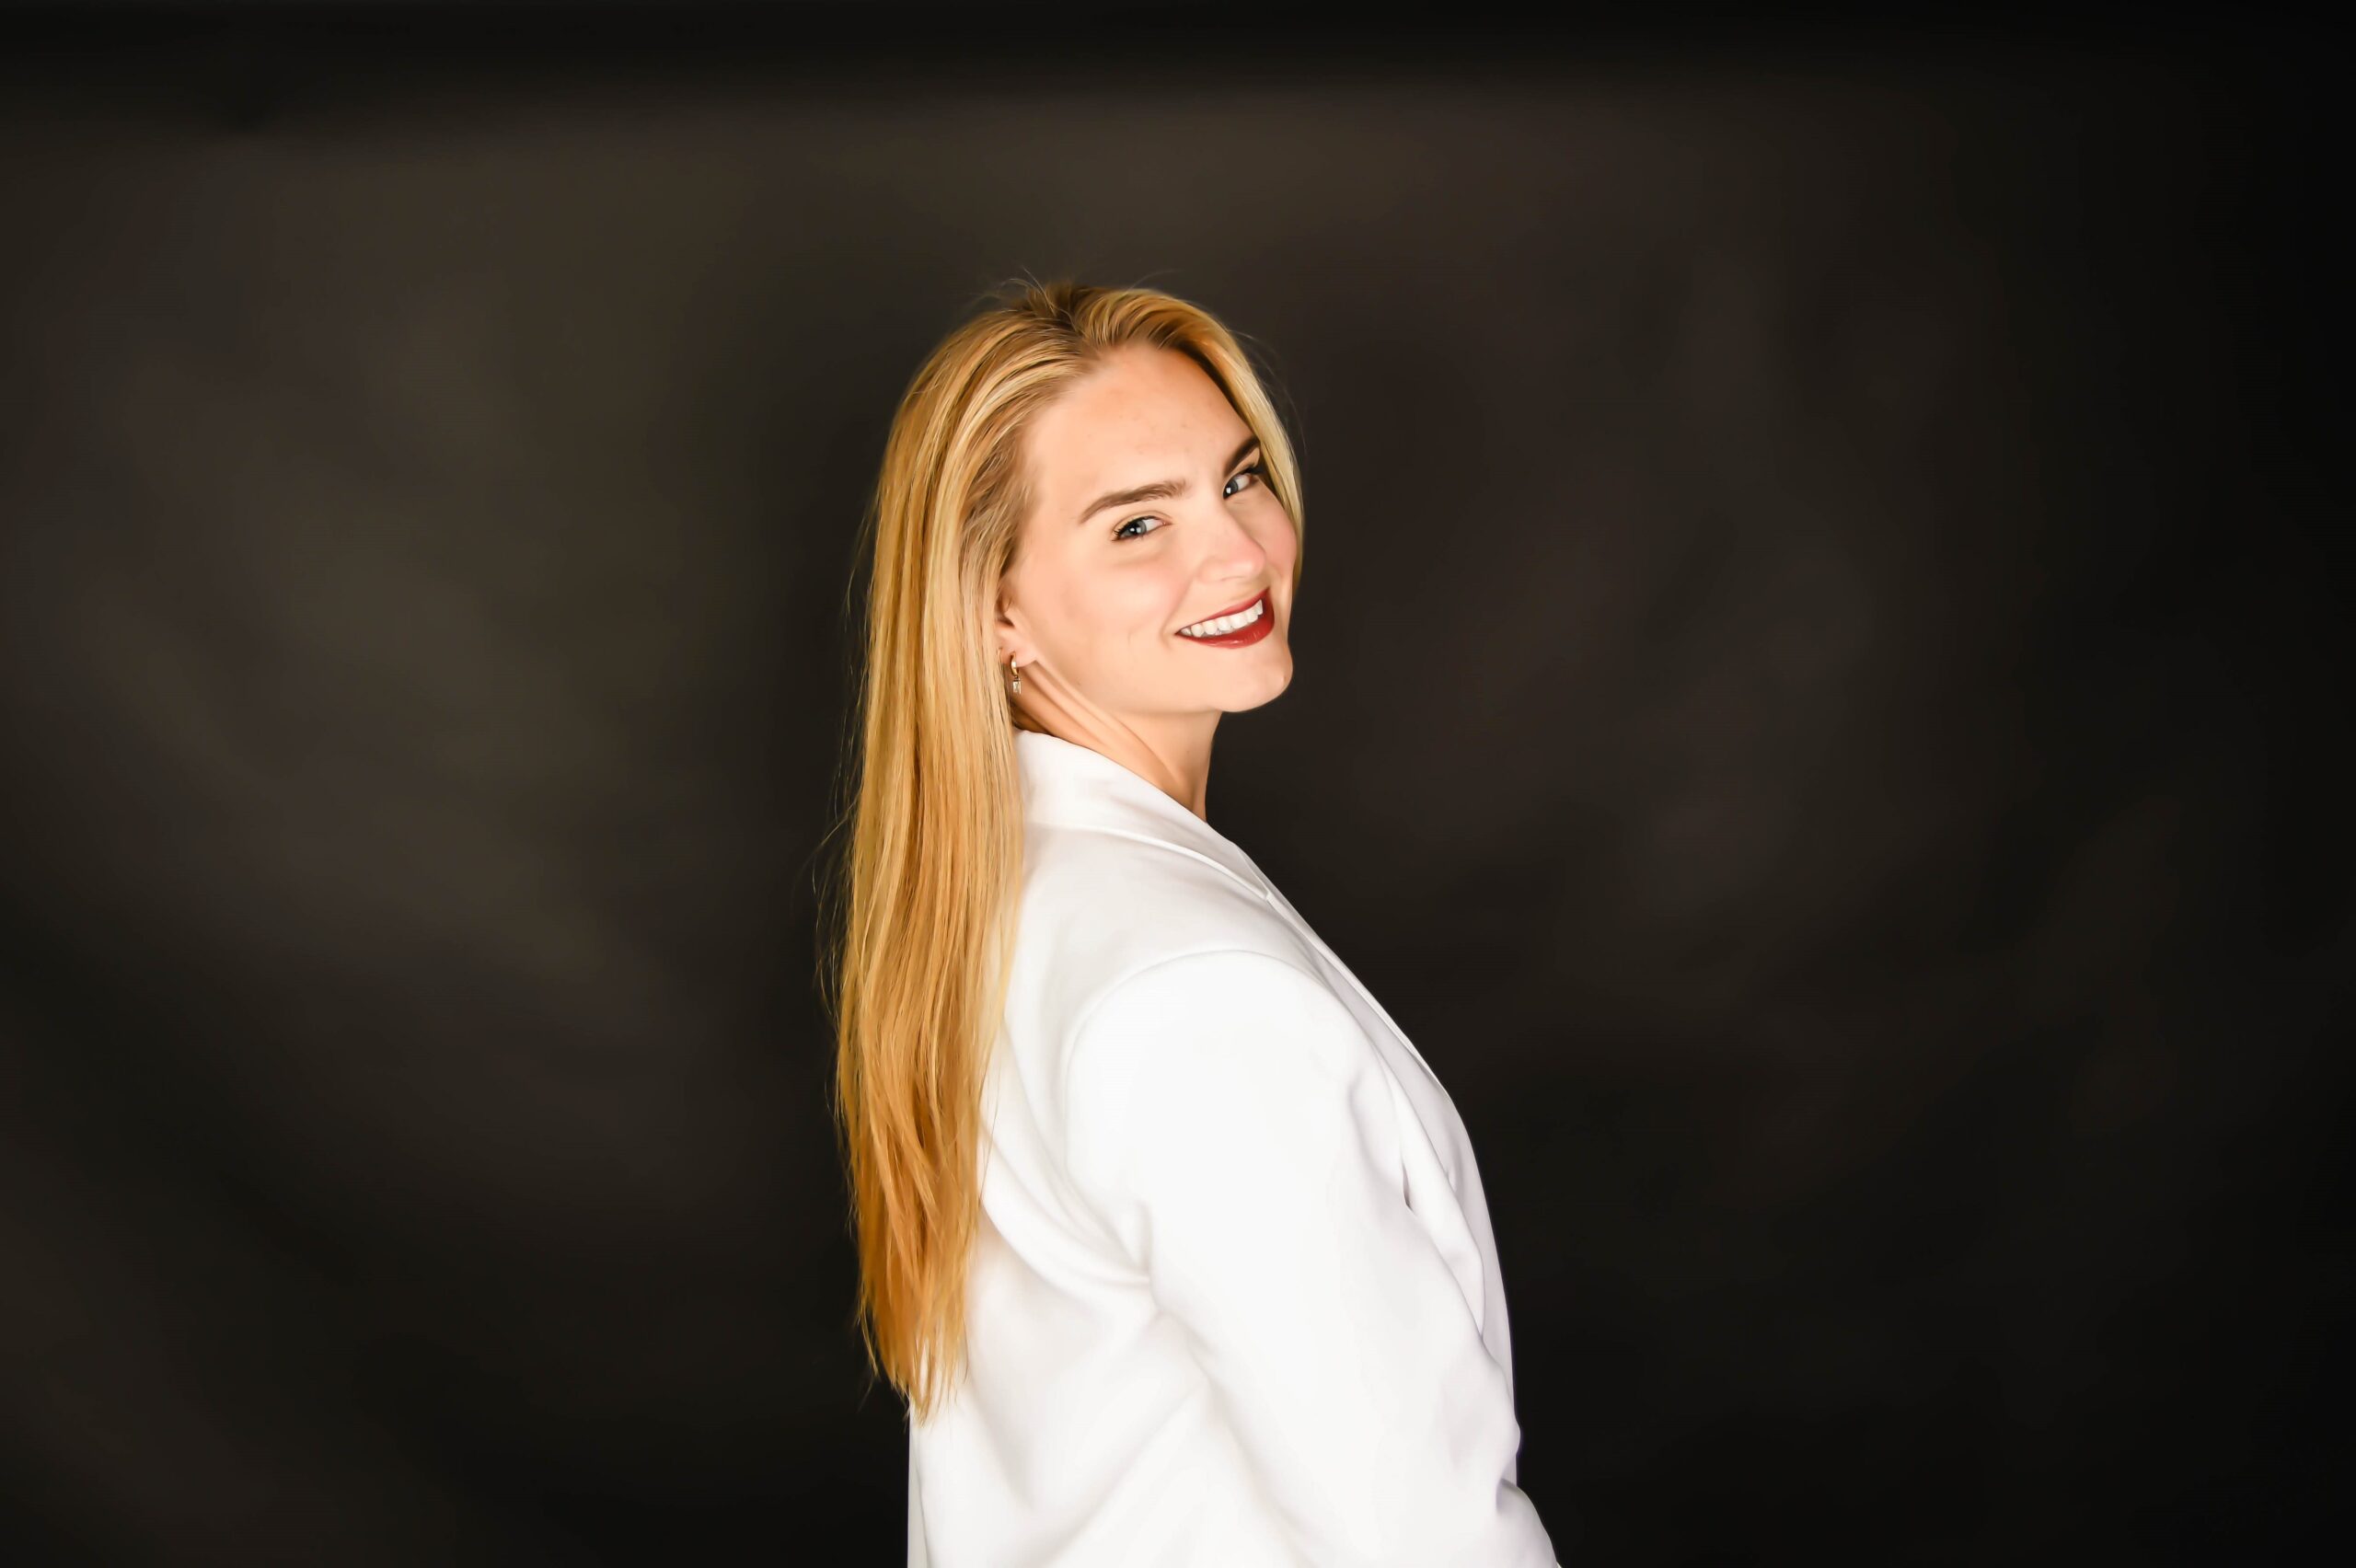
Jackie James has worked in the financial services and 529 industry since 2018 and currently serves as a Director at TIAA-CREF Tuition Financing, Inc. (TFI), a wholly-owned subsidiary of TIAA. TFI operates as the 529 Plan Program Manager for the States of California, Georgia, Illinois, Kansas, Michigan, Minnesota, Oklahoma, Washington, and Wisconsin.
In her role, Jackie has successfully managed strategic programs and initiatives that consistently drive business growth, with expertise in developing and executing marketing plans for the Edvest 529 College Savings Plan and Bright Start 529 College Savings Plan. She holds two Bachelor’s degrees in Marketing and Entrepreneurship from the University of South Carolina, and a Master’s degree in Project Management from the University of Maryland Global Campus. Jackie resides in the Greater Asheville area with her husband and two cats, and is passionate about youth mental health, volunteering as a Volunteer for the Guide Dog Foundation for the Blind and currently serving as the Sustainability Action Membership Co-Lead at TIAA.
*Information up to date as of November 1, 2025, GI Bill policies may change in the future.
1 U.S. Department of Veterans Affairs, “Post-9/11 GI Bill” (https://www.va.gov/education/about-gi-bill-benefits/post-9-11/)
2Internal Revenue Service, “529 Plans: Questions and Answers” (https://www.irs.gov/newsroom/529-plans-questions-and-answers)
3Apprenticeship programs must be registered and certified with the Secretary of Labor under the National Apprenticeship Act.
4SECURE Act 2.0, Public Law 117-328 (2022)
Please read the Plan Description on www.tiaa.org/529 carefully prior to investing, for details on its investment objectives, risks, charges, and expenses, and whether your home state offers tax or other benefits such as financial aid, scholarship funds, or protection from creditors for investing in its own 529 plan. More information about municipal fund securities is available in the issuer’s Plan Description. Investments in the plan are neither insured nor guaranteed and there is the risk of investment loss. Consult your legal or tax professional for tax advice. TIAA-CREF Tuition Financing, Inc. (TFI) is the Plan Manager for several state 529 plans, and TIAA-CREF Individual & Institutional Services, LLC, Member FINRA, is the distributor and underwriter for those plans.
Funds rolled over to a Roth IRA can be withdrawn free from federal and Wisconsin income tax. If you are not a Wisconsin taxpayer, these withdrawals may include recapture of tax deduction and state income tax. Account Owners and Beneficiaries should consult with a qualified tax professional before rolling over funds from their 529 plan to contribute to a Roth IRA.
Neither TIAA-CREF Tuition Financing, Inc., nor its affiliates, are responsible for the content found on any external website links contained herein. 4871409
As soon as Baby G was born, my husband and I decided that we needed to be the most prepared grandparents in the history of grandparents. Nana and Pops would win the game of responsible grandparenting and set our little peanut up for future success.
This responsibility worked itself out in a few very specific ways for us. We:
- Own the same stroller and car seat as G’s parents so that transport is never an issue;
- Stock diapers, wipes, and clothes so no “packing of the bag” is required to visit; and
- Opened our own 529 plan as soon as her parents had her Social Security number.
Now that G is the big 3, I can report that numbers 1 & 2 kept things easier for our family and removed stress from exhausted new-parent and eager-grandparent brains. Never having to worry about grabbing the car seat base or forgetting pj’s make hosting our now Big Girl a simple and smooth process.
Simple and smooth is also how I would describe opening our own 529 plan with our granddaughter as the beneficiary. We knew we wanted to select the investments and retain control of the funds, so we opened our own account very early. This has worked great for us, allowing a long-time horizon for her investments to grow. We anticipate a solid financial start, early conversations about education and career choices, and the satisfaction that she’ll have less student loan debt.
Most importantly, we’re modeling investing behavior across generations. While the trips to Disney are fun, we know that planning for her future with a 529 account is truly the ultimate grandparent flex.
About the Author:
Marissa Rowe is executive director of the Indiana Education Savings Authority, which administers the Indiana529 savings program with more than $8.4 billion in assets under management in three plans. A proud first-generation college student, Marissa received her B.A. in Mass Communication from the University of North Carolina at Asheville and her M.A. in Philanthropic Studies from the Indiana University Lilly Family School of Philanthropy. She paid off her student loans in 2020 and has 529 plans for her nieces and granddaughter.
By Colleen Davis, Delaware State Treasurer
July 29, 2025
Close your eyes and visualize college. What do you see? Most people would say classrooms, lectures, textbooks, essays, tests. Some might jump ahead to the last day, wearing a cap and gown and holding a diploma. Others might visualize a lush, green quad with students studying and socializing. Or you might see the opportunities to play sports, take part in activism, or – let’s be honest – party the night away.
The truth is that a higher education can encompass all these things and more – blending the people, the ideas, and the challenges we encounter into a mold that shapes us as people. With that in mind, I’d like to share some of the lessons I’ve gained from my own educational experiences.
Your Major Doesn’t Define Your Life
College is a great way to prepare for a career – but it doesn’t lock you into a rigid path. When I went to college for molecular biology, no one (including me) imagined I’d one day go into public finance.
As an undergrad, when I wasn’t in class or at soccer practice, I worked nights in the library. My job was to process inter-library loans – pulling books off the shelves and shipping them all over the world. In doing so, I started to expand my horizons as I was exposed to knowledge well outside the focus of my studies. It stimulated my curiosity and made me realize how much more there was out there to learn.
After graduating, I went to work as a scientific researcher for a biologics company. As exciting as the lab could be, I quickly realized that I needed more direct human connection in my career. So back to school I went for a master’s program to become a physician associate. Still no sign of public finance! That came much later.
It’s Not Just What You Know – It’s How You Think
Vital though it was for me to learn about cells, DNA, human physiology, and so on if I was going to be a molecular biologist, I gained far more value in school from learning how to think like a scientist.
Research isn’t something you can do on Google. It’s a process of developing hypotheses, figuring out how to test them accurately and effectively, and then interpreting your results. A good researcher doesn’t start with an answer – she starts with a question, she’s willing to challenge her own assumptions, and she follows the data wherever it leads.
But even students who don’t study science learn critical thinking – perhaps the greatest life skill of all. When you learn to think critically, you can solve problems that go far beyond work or school. It unleashes your mind to consider what’s working, what isn’t, and what to do about it. And when you surround yourself with other critical thinkers who are willing to challenge you as well as themselves, you can truly make magic together.
Today, with so much information accessible at a moment’s notice, it’s not as important as it once was to memorize every fact and formula. What matters is learning how to evaluate the facts in front of you in ways that foster understanding, innovation, and progress.
Leadership Is More Than Giving Orders
As a student athlete, I was just one player on the soccer team, but I was drawn to a leadership role. And in the process, I discovered that there were so many paths other than my own to reaching a common goal – like, say, scoring a goal.
Our team was a blend of people with different personalities, ages, life experiences, and priorities – and we all had to pull in the same direction. Of course, I quickly found that not everyone was going to do it my way. Instead, I learned to create space for my teammates to do the things they excelled at so that we could win together.
Leadership is about sharing accountability, creating mutual understanding, and putting your teammates in position to succeed. But reading it on this blog only does so much – you must go out and have those experiences for yourself.
Final Thoughts
More than degrees or credentials, my education has shaped how I think, how I work with others, and how I approach my duties as a leader. It has taught me to ask tough questions and to keep expanding my horizons. As much as I’ve learned about medicine, business, and finance, I could not have applied it nearly as effectively if not for these skills I picked up along the way.
That’s why I believe so strongly in the value of higher education – and why I work hard to make it more accessible. As a parent of three in Delaware, I know personally what it’s like to be intimidated by the cost of college. It’s never been more important to start saving for college as soon as possible, and I’m proud to facilitate my state’s 529 plan, which helps families get ahead of all those expenses.
You don’t have to know exactly where your children’s education will take them, but when you give them the chance to learn, grow, and forge their own paths, the possibilities are truly endless.
About the author:
Colleen C. Davis has served as Delaware’s State Treasurer since 2019, focusing on three main priorities: bolstering retirement security and readiness through Delaware’s DEFER and EARNS programs, creating pathways to economic empowerment through plans such as DE529 and DEpendABLE, and promoting a culture of financial excellence. Treasurer Davis currently serves on the CSPN Executive Board.
The 2025 NAST Legislative Conference brought members of the College Savings Plans Network (CSPN) to Washington, D.C., for a high-impact week of advocacy, networking, and policy engagement. As 529 plans continue to play a vital role in helping American families prepare for the cost of education, this year’s conference offered a timely opportunity to raise awareness of current challenges and promote key policy solutions. CSPN members participated in a range of sessions and meetings that focused on enhancing the effectiveness of 529 plans and increasing access for families across the country.
One of the key policy themes discussed was the need to align federal financial aid methodology with the goals of 529 savings. CSPN continues to advocate for changes that would exempt 529 plan balances from being treated as parental assets in FAFSA calculations—an adjustment that would remove one of the most cited deterrents to account participation. In addition, members promoted legislation that would expand 529 plan uses to include postsecondary credentials and career-aligned programs, helping families save not just for college, but for a range of workforce development opportunities.
CSPN’s Federal Initiatives Committee convened during the conference, reaffirming the network’s federal priorities for the coming year and coordinating outreach strategies for engaging Congress. With more than 16.9 million open accounts and over $526 billion saved in 529 plans nationwide, CSPN’s voice remains a critical one in conversations about the future of education access and affordability.
A highlight of the conference was the presentation of the Chris Allen Memorial Award for Outstanding Advocacy in Public Finance, which honors individuals who have made a lasting impact in advancing NAST’s federal priorities. Two of this year’s honorees, John Stevens, Director of the Bureau of Savings Programs at the Pennsylvania Treasury, and Nicola Bunick, Deputy General Counsel and Federal Policy Advisor at the Illinois State Treasury were recognized in part for their leadership on college savings issues. John has provided long-standing service to CSPN through leadership, expertise, and program excellence. Nicola has been instrumental in advancing CSPN priorities at the federal level through strategic policy work and advocacy support.
As Congress considers new tax and education legislation, CSPN members left the conference energized and united in their mission to ensure that 529 plans continue to evolve in ways that meet the needs of today’s students and tomorrow’s workforce.
About the author:
Dillon Gibbons is the Director of Policy at the National Association of State Treasurers (NAST).
The latest 2024 data for 529 college savings plans is in, and the numbers are impressive! With over 16.96 million accounts nationwide, 529 plans are continuing to gain traction as the go-to tool for saving for higher education. Collectively, families have saved a staggering $525 billion in these plans, with the average account size reaching $30,966. That is an 11% increase in the amount of money saved since 2023!
This strong growth demonstrates a growing awareness of the importance of saving early for education expenses. 529 plans are designed to make saving for college easier, offering tax-free benefits when used for qualified education expenses. These plans are ideal for families looking to build an education savings fund over time.
The 2024 data highlight the success of these plans and reinforces the importance of starting to save now. Whether you’re saving for a child’s education, your own, or even for a grandchild, a 529 plan offers flexibility and valuable tax advantages. Plus, it’s never too late to start—setting up an account today can help ease the financial burden of rising tuition costs.
If you haven’t already, consider taking advantage of the benefits of a 529 plan. With millions of accounts already in place and over half a trillion dollars saved, now is the perfect time to join the growing number of families investing in education for a brighter future. Start saving today, and set yourself up for success tomorrow!
About the author:
The College Savings Plans Network (CSPN) is a leading objective source of information about Section 529 college savings plans and prepaid tuition plans–popular, convenient, and tax-advantaged ways to save for college. An affiliate of the National Association of State Treasurers (NAST), CSPN brings together state officials who administer 529 savings and prepaid plans from across the country, as well as their private-sector partners, to offer convenient tools and objective, unbiased information to help families make informed decisions about saving for higher education.
By Dave Dominick, Assistant Director of Marketing and Outreach for the Pennsylvania Treasury Department
February 18, 2025
List of “must haves” for a competitive benefits package.
- Professional development. Check.
- Flexible work-life balance. Check.
- On-site childcare. Check.
- Pet-friendly office. Check.
- 529 matching for my kids. *Crickets chirping*
That sound of silence is about to get loud. For years, 529 plans have been helping families steadily and strategically save and pay for education expenses. According to the College Savings Plans Network (CSPN), families had more than $508 billion tucked away in tax-advantaged 529 accounts as of June 2024. This money can help pay for a loved one to become anything from an electrician to a teacher, depending on their chosen career path.
Though the amount in 529 plans has nearly doubled in the last decade, it is considerably less than the amount Americans have in retirement accounts. Data from the Investment Company Institute shows that retirement accounts hold more than $40 trillion. To put this into perspective, that’s roughly 7,700 times more than 529 plans.
Outreach is Key
One of the main reasons people save more for retirement is because most companies offer various savings options to employees on day one as part of a comprehensive benefit package, many times including matching contributions.
To make it easier to save for retirement, companies can offer 401(k) plans, individual retirement accounts (IRAs), deferred compensation plans, and more. Most often, employees set up these accounts as soon as they are hired and save steadily through automatic payroll deductions with each pay. By saving automatically, employees are less likely to miss a contribution. As the saying goes, “Slow and steady wins the race.”
Unfortunately, according to a report by Statista, only 10 percent of companies nationally offer workplace payroll deductions for 529 education savings accounts.
However, a growing number of employers are offering 529 plans as a voluntary benefit. Employees can pick a 529 plan and contribute using payroll deduction, and many state-sponsored 529 plans have outreach and education specialists to help both employers and employees navigate this process.
State agencies that manage both 529 and unclaimed property programs can find it easier to connect with new businesses. Outreach teams can identify unclaimed property owed to a business and use that as a perfect reason to begin a conversation that may lead to a meaningful relationship and additional resources for employees.
Offering a Business Tax Credit
There are other beneficial reasons employers may begin offering 529 plan access in the workplace. At least eight states now have laws that provide tax credits to companies that match employee contributions to 529 plans. In Pennsylvania, the latest state to offer a business tax credit, employers can claim a 25 percent tax credit on matches to employee 529 (and ABLE) contributions of up to $500 per employee. The Pennsylvania Treasury Department’s outreach team has already formed relationships with statewide and regional chambers of commerce to help engage employers.
By promoting a state tax credit for 529 contribution matching and emphasizing improving employee benefits and workplace culture, employers can see the long-term economic and social impact their contributions can have on helping create a more educated workforce for local communities.
An October 2024 article in the New York Times provided more examples of employers offering 529 plan matching contributions.
Resources
A Commonwealth report noted that most employees were interested in saving in 529 plans, especially those from low—and moderate-income households. There has never been a better time to approach employers about this important opportunity. The Commonwealth report outlines these opportunities and offers suggestions and best practices for employers to use when implementing a workplace rollout of access to 529 plans.
Many states also offer and promote Children’s Savings Account (CSA) programs like Pennsylvania’s Keystone Scholars, which provides a $100 investment for post-high school education for all babies born in Pennsylvania since 2019. Awareness of CSAs helps new parents understand the importance of saving early, starts them on their savings journey, and increases parental expectations for their child’s future.
What’s Next?
State 529 plan industry groups, like CSPN, remain engaged with lawmakers in Congress to enhance education savings accounts. Over the last ten years, 529 plans have expanded to include K-12 tuition expenses, apprenticeships, and student loan repayment as qualified expenses.
This, in part, has spurred the popularity and growth of 529 plans nationwide. Other initiatives, such as incentives to open accounts (see 529 Day activities), matching employer contributions at the state level, and increasing access to technology to manage accounts, are steps in the right direction.
Your company can contact your state’s 529 plan office to discuss potential outreach and learning opportunities. CSPN’s website maintains a search tool for 529 plans nationwide.
About the author
Dave Dominick is the Assistant Director of Marketing and Outreach for the Pennsylvania Treasury Department’s Consumer Programs, which includes the Pennsylvania 529 College and Career Savings Program, Keystone Scholars, and the Pennsylvania ABLE Savings Program. He also co-chairs the ABLE Savings Plans Network’s Data and Benchmarking Committee.
By Trisha Good, Executive Director, Ohio Tuition Trust Authority
January 21, 2025
As we settle into the new year, is one of your resolutions improving your family’s financial health? If so, there are many ways for everyone to learn healthy money habits. Here are some ideas for how to save as a family and have fun while doing it.
Board games
Board games are a fun way to learn valuable life lessons. Choose ones that teach basic principles of personal finance, like the Game of Life, Pay Day, or Monopoly. Some games specifically focus on money management techniques like Cash Flow 101. For a more comprehensive list of board games to teach personal finance skills at different ages, this article lists 53 options. As your family plays these games together, your children can learn core financial concepts to help them in the future.
Books
Reading with your child or grandchild builds their language skills. Reading age-appropriate money books together builds their understanding of how money works and how they can make money work for them. It also allows them to ask questions of you, which can demystify talking about finances with them and can allow for more open communication. And reading these books together also allows you to brush up on your financial basics as well. Here are some money books with which to begin.
Learning how to save
If your children are young, introduce them to basic budgeting concepts with spend, save, and share jars. They can watch how Elmo from Sesame Street saves in those three jars. After earning money from their allowance or completing chores, talk to them about the value of saving now so they can use it later.
For teenagers, show them how to set up a budget to pay for their smartphone, buy gas, or save for their education after high school. Another idea is to give your teenagers money to get school clothes money once per year so they can choose how to spend the funds. This way, they can see how much or how little they can buy, depending on their own personal spending decisions. It’s better to learn what things really cost now to set their financial priorities better later in life.
Parent Magazine also offers guidance on money lessons to teach your children at every age.
Set and incentivize savings goals
Talk to your children about something they would like to have, like a new phone or video game. Then, help them come up with a plan to reach their savings goals. By breaking down their savings goals into small chunks based on their allowance or summer job, they can learn how to budget and then track their progress.
To keep them motivated, you can offer incentives for when they reach new levels with their savings goal. It can be something small like an ice cream cone if they are younger, or you can offer to pitch in a defined dollar amount once they have reached a certain percentage of their goal.
Saving in a 529 plan
Let your children know you are saving for their college and career training. You don’t need to share the dollar amount saved in your 529 account, but you should set your expectations with them–that they will be continuing their education after high school.
Research from the Institute for Higher Education Policy shows that when children know that there are college savings set aside for them, they are much more likely to expect to attend college. In fact, children with $1-$499 in college savings are three times more likely to attend college and four times more likely to graduate than those with no savings.
529 plans are for whatever school comes after high school for your children and grandchildren. Funds in a 529 account can be used tax-free for qualified higher education expenses at four-year colleges or universities, two-year community colleges, trade or vocational schools, apprenticeships, or certificate programs. So, your children can go to a school where their interests, talents, and skills lie.
To learn more about 529 plans, visit My State’s 529 Plan on College Savings Plans Network’s website to learn about all the tax advantages and benefits of saving in your home state’s 529 college and career training program.
About the author:
Trisha Good is the executive director of Ohio Tuition Trust Authority. Since 1989, Ohio Tuition Trust Authority has sponsored and administered Ohio’s 529 College Savings Program, CollegeAdvantage. Ohio’s 529 Plan oversees more than 678,700 accounts and over $18.2 billion in assets as of December 31, 2024. Visit CollegeAdvantage.com or call 1-800-AFFORD-IT (233-6734) for more information.